🔔 Read us on Telegram — don’t miss the latest automotive news → t.me/motorhub_en
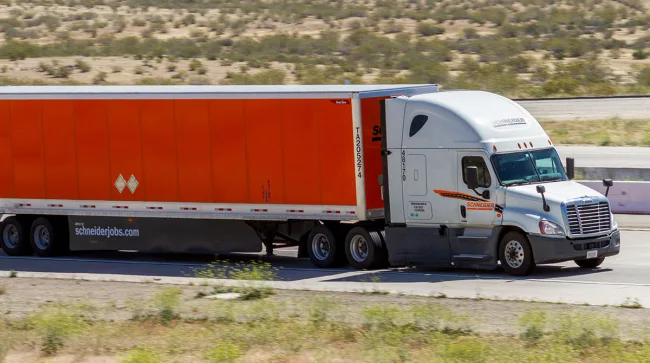
Wisconsin-based truckload giant Schneider reported a 10% revenue jump to $1.57 billion in Q2 2026, with net income rising to $49.7 million from $36 million a year earlier. The company’s executives attribute the improved freight-market conditions to accelerated driver-capacity reductions, which have outpaced earlier expectations and removed what they call “irrational capacity.” Schneider now describes the market as driver-constrained, with roughly half of the remaining noncompliant capacity expected to exit by next year. Spot rates have already surpassed prior-cycle highs, turndowns remain elevated, and utilization has climbed meaningfully. Schneider President Jim Filter told investors on July 30 that underlying demand has been largely stable, with modest seasonal activity, and that the market improvement has been supply-led. He added that spot rates now exceed contract rates at levels historically linked to stronger contract pricing. However, the tightening supply is also inflating driver-recruiting and retention costs, forcing Schneider to realign pay structures to reward top performers, add recruiters, and expand AI use. The company is targeting $40 million in cost savings while pursuing contract gains and reallocating capacity to high-demand, high-productivity lanes. Schneider’s dedicated operations are expected to benefit as contract renewals and allocation decisions translate into improved pricing power. Segment results showed Truckload revenue up 1% to $627.6 million, Intermodal revenue down 1% to $262 million, and Logistics revenue up 11% to $376.1 million. Schneider ranks No. 10 on Transport Topics’ Top 100 for-hire carriers in North America, No. 18 among the largest logistics companies, and No. 50 among the largest global freight companies.
📱 Follow our Telegram channel for daily updates
Source: Transport Topics — Michelin & Tires (EN) (ttnews.com)